



 0

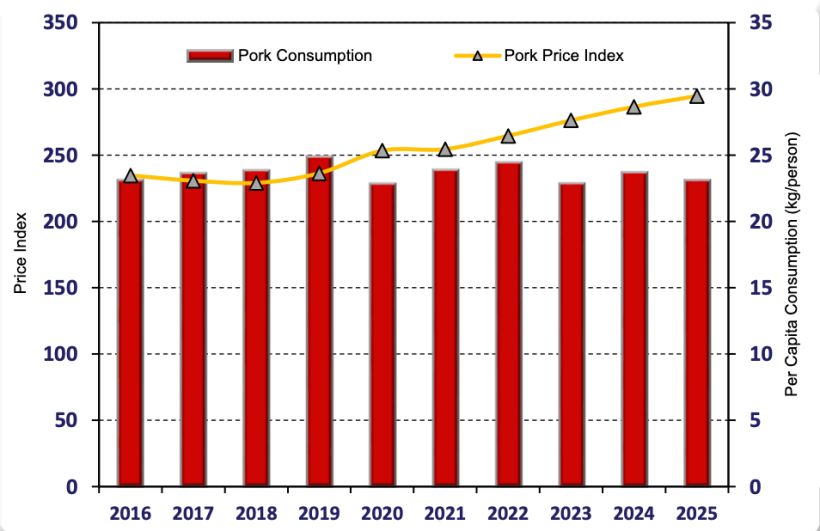
Australian pork production is forecast to remain broadly flat (+0.6%) at 475,000 MT (CWE) in 2027, compared with an estimated 472,000 MT in 2026 and 475,000 MT in 2025. At first glance, producer economics appear supportive: baconer prices rose strongly from early 2024 while feed grain prices declined and remained relatively subdued for much of 2025 and early 2026. However, the production response has been much weaker than the margin signal alone would suggest.
The key constraint is downstream demand rather than farm-level feed economics. Australian fresh pork is effectively supplied by domestic producers because biosecurity restrictions prevent imported chilled pork from being sold as fresh pork. Imported frozen pork is therefore concentrated in manufactured products such as ham, bacon and smallgoods. When fresh-pork retail prices rise faster than competing proteins, processors and retailers cannot substitute imported pork into the fresh market; instead, they can reduce promotions, adjust cut mix, or limit pig procurement. Pork prices have risen faster than poultry and, for periods, faster than beef, weakening pork’s relative value proposition and constraining the demand signal passed back to producers.
Population growth will support underlying demand, but continued pressure from lower-cost poultry and competitive imports of processed pork will limit the price and volume signals required for a material increase in domestic pig production.
Australian pork consumption is expected to increase by 0.8% to 655,000 MT (CWE) in 2027 from an estimated 650,000 MT in 2026. The increase is driven by population growth, while per capita pork consumption is expected to continue its gradual decline.
Australian pork imports are expected to remain unchanged at 220,000 MT (CWE) in 2027, after rising from 214,000 MT in 2025 to an estimated 220,000 MT in 2026. Import sourcing has shifted. Prices from major European suppliers declined more sharply than U.S. prices, improving the competitiveness of Denmark, the Netherlands, and other EU suppliers and reducing the U.S. share from 51% in January-June 2025 to 37% in the same period in 2026.
Australian pork exports are forecast to decline by 4.8% to 40,000 MT (CWE) in 2027 from an estimated 42,000 MT in 2026 and 46,000 MT in 2025. Exports remain small relative to domestic production and are therefore highly sensitive to individual destination demand, freight costs, and Australia’s price competitiveness against larger global suppliers. Shipment to Singapore, historically Australia’s largest pork export destination, fell in the first half of 2026. By contrast, exports to Papua New Guinea increased.
September 28, 2026/ USDA/ United States.
https://www.fas.usda.gov/