



 0

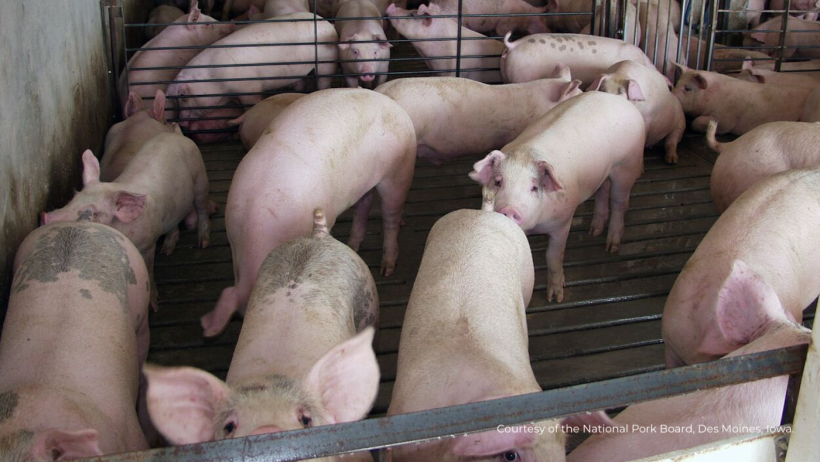
Lower pork prices in the last quarter of 2025 and through the first half of 2026 contributed to the exit of inefficient farms from the market and a consequent drop in animal inventory. The situation is expected to stabilize somewhat in 2027 as industrial farms continue to build their inventories despite the challenges.
Pork production in Ukraine is concentrated in clusters near major feed sources and consumers. Eastern pork production segments ceased to exist in 2022 after the full-scale invasion started, and many farms relocated their production facilities to western Ukraine, although production in central Ukraine, especially around Kyiv, remains significant. Industrial farms comprise 69% of the swine inventory and household production 31%.
African swine fever (ASF) remains a major risk factor, as it is difficult to control in front-line regions. ASF is also the main production expansion risk factor, and disease spread in the wild and in nearby households is beyond investors’ control. The number of ASF cases grew after the full-scale Russian invasion in 2022 but stabilized by 2025. Industry sources confirm a relatively stable number of incidents in 2026.
Insignificant growth in swine inventories in 2027 will result in limited growth in pork production, expected to reach 610 thousand MT. In 2026, pork production will also remain sluggish, depressed by weak retail prices and stronger imports. Increased Russian attacks on Ukrainian infrastructure may negatively impact pork production in the winter months of 2026/27. Slaughterhouse and cold storage facility operations remain prone to energy shortages and logistical issues. Labor shortages reported by swine producers will also impact processing and pork distribution.
The ongoing pork price drop and increased import of pork products will facilitate a modest increase in pork consumption in 2026 and 2027. Pork is a traditional, popular protein, and consumers switched to it after beef prices rose in the last quarter of 2025.
Russian attacks on food and cold storage logistics, which intensified in spring/summer of 2026, could become a significant factor affecting pork consumption in 2026-2027. Many large retail chains lost their distribution centers to Russian attacks, prompting some retailers to return to individual direct deliveries from producers. Other retailers requested producers to share up to 100 percent of the cost of lost product in attacked distribution centers. Although negotiations are underway, retail pork price increases, driven by higher logistics costs, seem unavoidable moving forward.
Import demand will remain strong in 2027 at 45 thousand MT, as growth in the industrial sector will not compensate for the reduction in household inventory. Due to geographical proximity and historical ties with European pork producers, the EU remains the major supplier, with Canada being the only other pork exporter to Ukraine.
September 28, 2026/ USDA/ United States.
https://www.fas.usda.gov