Global swine production: USDA's initial estimates for 2027
October 13, 2026/ 3tres3 Latin America with data from USDA.
28-Oct-2026 (today)In its report “Livestock and Poultry: World Markets and Trade,” published on October 9, the USDA projects that global pork production will decline by 0.7% in 2027 due to declines in China and the European Union, while African swine fever (ASF) in Spain and weak Chinese demand will reshape international trade.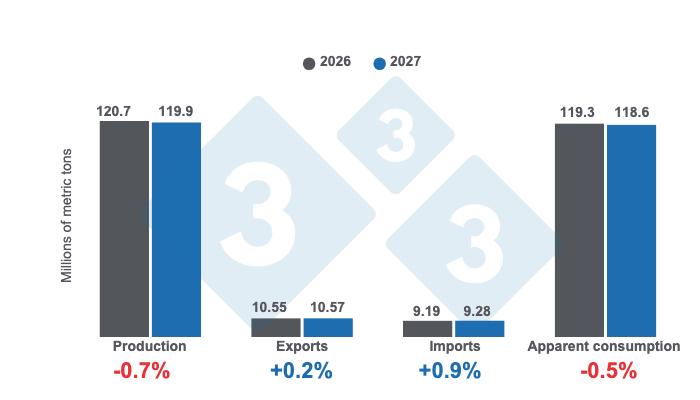
General forecasts
- Global pork production is expected to decline slightly in 2027, as declines in China and the European Union would outweigh gains in Brazil, Vietnam, and the U.S. In China, the decline would be driven by a government-led reduction in the hog herd and low profitability in the sector, while in the EU, high domestic supply in 2026 and pressure from environmental regulations would weigh on production.
- Global exports are expected to remain virtually unchanged following the increase in 2026, as higher shipments from Brazil, China, the U.S., and Mexico would offset the decline in the European Union. During 2026, increased export supply weakened international prices: through July, the unit value of exports fell by nearly 9% in the EU, 2% in Brazil, and marginally in the U.S. Major importers took advantage of this supply, and through June, purchases by Japan grew by 5%, those by South Korea by 18%, and those by the Philippines by 1%—the latter following a record high in 2025 and with domestic production on the mend. However, pork inventories in these countries continued to rise through July, causing the pace of imports to stagnate in South Korea and the Philippines and to moderate in Japan during the second half of the year, which would intensify competition among exporters.
- The disruptive factor during this period was the detection ASF in wild boar in Spain in November 2025—the first such case since 1994. Japan, the second-largest non-EU market for Spanish pork, along with Malaysia and Taiwan, continues to enforce restrictions. In contrast, China and South Korea quickly implemented regionalization, and the Philippines—the fifth-largest non-EU market—recognized it in May 2026. Despite the outbreak, Spanish production increased through June by redirecting products to other EU member states and expanding shipments to South Korea, Vietnam, and the U.S., while Denmark and France partially filled the gap in the restricted markets. This reallocation likely increased the available supply in the EU and put downward pressure on prices.
Global indicators
- Global production is projected to reach 119.9 million metric tons (Mt) in 2027, representing a 0.7% decline from 2026 (120.7 Mt).
- Global exports are expected to reach 10.57 Mt, a slight increase of 0.2% compared with the previous year.
- Imports, meanwhile, are expected to total 9.28 Mt, representing a 0.9% increase compared to 2026.
- Apparent consumption is expected to reach 118.6 Mt, 0.5% below the estimated volume for the previous year.
Key indicators by country
- China is projected to produce 58.4 Mt in 2027, a 2.2% decline compared to 2026. Imports are projected to total 820,000 metric tons (t), down 2.4%, while exports are expected to grow by 21.2% to 200,000 t, the highest volume since 2018.
- The European Union is projected to produce 22.0 Mt, down 0.5% from the previous year. Similarly, its exports are expected to decline by 3.3% to 2.95 Mt, due to lower available supply and increased competition in its main markets.
- The U.S. is projected to produce 12.6 Mt, a 0.7% increase driven by a higher number of piglets per litter, despite a smaller breeding herd. Meanwhile, exports are projected at 3.22 Mt, which would represent a 0.6% increase, supported by robust demand from Mexico and Canada.
- Brazil is projected to reach 5.14 Mt, 2.8% higher than in 2026, thanks to improvements in production efficiency and higher carcass weights. Similarly, its exports are expected to increase by 2.5% to 1.85 Mt, a more moderate pace than in recent years
- Vietnam is expected to increase its production by 3.5%, reaching 4.20 Mt, driven by strong domestic demand and favorable pig prices. Its imports are projected to total 155,000 t, up 3.3% from the previous year.
- Japan's production is expected to remain close to 1.28 Mt, with a slight decline of 0.4%. In contrast to the trend in 2026, its imports are expected to fall by 2.0% to 1.48 Mt, given high domestic inventories.
- Mexico is projected to produce 1.49 Mt, representing a 3.1% increase. Imports are expected to total 1.76 Mt, up 3.5% from 2026, while exports are projected to rise 9.1% to 240,000 t, driven by a recovery in production following animal diseases and higher-than-expected demand from the U.S. and Japan.
- Canada is projected to reach 2.24 Mt, representing a 2.3% increase. Its exports are expected to remain unchanged at 1.30 Mt, while imports are projected to decline by 8.9% to 205,000 t.
- Colombia is projected to reach 735,000 t, a figure that would represent a 4.3% increase compared to 2026. In contrast, its imports are expected to fall by 2.7%, to 180,000 t.